Euribor in 2026: Impact on Your Mortgage and What to Do
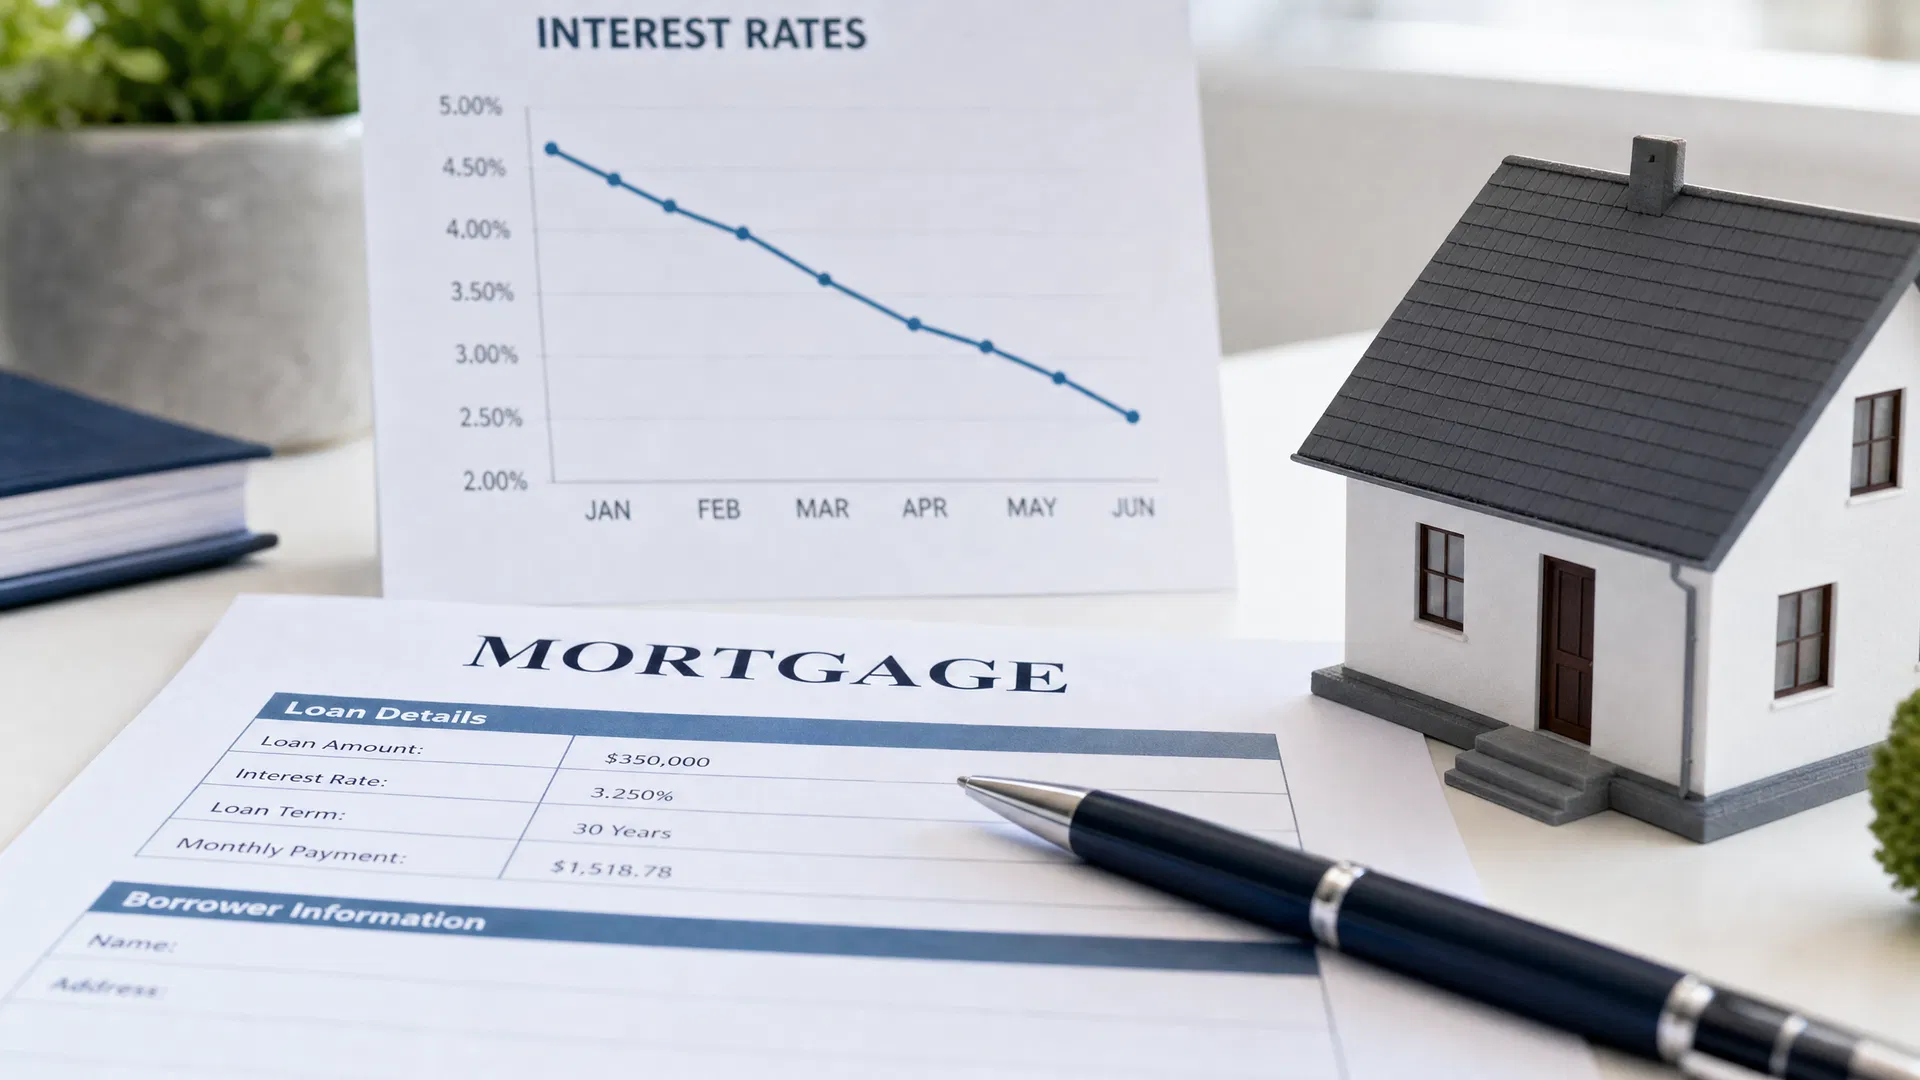
The 12-month Euribor reached a peak of 4.16% in October 2023, adding hundreds of euros to monthly mortgage payments for millions of European homeowners. Since then, the European Central Bank has been cutting rates, and the Euribor has followed — reaching approximately 2.0–2.5% in 2026. For borrowers, this shift represents both relief and a strategic decision point.
How Euribor Affects Your Mortgage
In Portugal, Spain, and most of Southern Europe, the majority of home loans are variable-rate mortgages indexed to the 12-month Euribor plus a bank spread (typically 0.8–1.5%). When the Euribor rises, so does your monthly payment — and vice versa.
The practical impact of the current Euribor decline is significant:
| Mortgage Amount | Rate at 4.5% | Rate at 2.5% | Monthly Saving |
|---|---|---|---|
| €150,000 | €760/month | €593/month | €167/month |
| €200,000 | €1,013/month | €790/month | €223/month |
| €300,000 | €1,520/month | €1,186/month | €334/month |
30-year term, spread of 1.0% included.
Fix or Float? The 2026 Dilemma
With Euribor having fallen substantially from its peak, many borrowers face a classic dilemma: lock in a fixed rate now, or continue with the variable rate hoping for further declines?
Fixed rates in Portugal and Spain in 2026 are typically in the 2.8–3.5% range for 20–30 year terms. If you believe the Euribor will stabilise or rise again — which some analysts project as the ECB balances inflation and growth — fixing now provides certainty.
The PropCalc Mortgage Calculator allows you to model both scenarios side by side.
Should You Overpay Your Mortgage?
With rates lower than in 2023–2024, the opportunity cost of overpaying your mortgage has changed. When Euribor was above 4%, overpaying was almost always the rational choice — the guaranteed return (saving 4%+ in interest) was hard to beat risk-free.
At 2.5%, the calculus is less clear. The S&P 500 has historically returned ~10% per year nominally. After Portuguese capital gains tax (28%), the net return is approximately 7.2% — well above the 2.5% mortgage rate. This suggests that, for many borrowers in 2026, investing surplus capital in diversified equities may generate better long-term outcomes than overpaying the mortgage.
Use the PropCalc Mortgage vs Invest Calculator to model your specific situation with your actual loan balance, rate, and investment horizon.
Key Actions for 2026
If you have a variable-rate mortgage, request a rate review from your bank — many lenders will renegotiate spreads to retain customers. If you are considering buying, the improving Euribor environment makes 2026 a more favourable entry point than 2023–2024 from a financing perspective. And if you are an investor, lower financing costs directly improve the cash-on-cash return of buy-to-let properties.
Euribor in 2026: Impact on European Mortgages
The evolution of Euribor is the factor that most directly affects mortgage payments for millions of European homeowners with variable-rate mortgages. Understanding how it works and what to expect in 2026 is essential for effective personal financial management.
How Euribor Works
Euribor (Euro Interbank Offered Rate) is the reference rate for the European money market, calculated daily based on the rates at which major European banks lend money to each other. There are several maturities: 1 week, 1 month, 3 months, 6 months, and 12 months.
Most variable-rate mortgages in Europe are indexed to the 6-month Euribor, with semi-annual revision.
The 2022-2025 Rate Cycle
The ECB launched in July 2022 the most aggressive rate-hiking cycle in decades, raising the deposit rate from -0.5% to 4% in just 14 months. The 6-month Euribor rose from negative values (-0.5% in 2021) to a peak of ~4% in 2023.
From June 2024, the ECB began a cutting cycle, gradually reducing rates. In 2025, the 6-month Euribor stabilised around 2.2-2.5%.
Impact on Monthly Payments in 2026
For a typical €150,000 mortgage over 30 years:
| 6M Euribor | Spread 1% | Monthly Payment |
|---|---|---|
| -0.5% (2021) | 1% | ~€450 |
| 4.0% (2023) | 1% | ~€750 |
| 2.5% (2025) | 1% | ~€630 |
| 1.5% (2026 forecast) | 1% | ~€570 |
Rate Risk Management Strategies
Fix your rate: Many banks offer the option to convert from variable to fixed rate. With Euribor falling, this may be a good time to lock in if you're risk-averse.
Early repayment: With low early repayment charges on variable-rate mortgages, overpaying is an attractive option when you have available capital.
Refinancing: If your current spread exceeds 1.5%, it may be worth negotiating better terms with your bank or transferring to a competitor.
Use our Mortgage Calculator to simulate the impact of different Euribor scenarios on your monthly payment.
Negotiating Agent Fees
Many buyers and sellers don't realise that agent commissions are negotiable. In competitive markets, agents may accept lower fees to secure a listing. Here are proven strategies for negotiating:
Start by researching local market rates. In Portugal, commissions typically range from 3-5% plus VAT. In the UK, fees range from 0.75% to 3.5%. In Germany, the buyer and seller usually split the Maklercourtage (typically 3-6% total). Understanding your local norm gives you leverage.
Consider offering exclusivity in exchange for a lower rate. Agents prefer exclusive listings because they guarantee a return on marketing investment. A 90-day exclusive at 3% may be more attractive to an agent than a non-exclusive at 5%.
Volume matters. If you're buying multiple investment properties, negotiate a portfolio rate. Many agents will offer 1-2% for investors who bring repeat business.
Hidden Costs Beyond Commission
Agent fees are just one component of transaction costs. Factor in these additional expenses when calculating your total cost of buying or selling:
- Solicitor/notary fees (typically 0.5-1.5% of property value)
- Land registry fees
- Survey/valuation costs (£300-£1,500 in the UK)
- Energy Performance Certificate (mandatory in most EU countries)
- Mortgage arrangement fees (if applicable)
- Moving costs and insurance
In Portugal specifically, the buyer pays IMT (property transfer tax), Imposto de Selo (stamp duty), and notary fees — which together can add 7-10% to the purchase price. Our Transfer Tax Calculator helps you estimate these costs precisely.
When to Use a Buyer's Agent
Buyer's agents (or property finders) charge separately from the seller's agent. They work exclusively for you, searching for properties that match your criteria and negotiating on your behalf. This service typically costs 1-3% of the purchase price or a fixed fee.
Consider a buyer's agent when: you're purchasing in an unfamiliar market, you're an overseas buyer, the market is highly competitive, or you're looking for off-market opportunities. The fee often pays for itself through better negotiation outcomes.
Impact on Investment Returns
For property investors, agent fees directly impact your return on investment. On a €200,000 property with a 5% selling commission, you're paying €10,000 — which could represent an entire year's net rental income.
Use our Fix & Flip Calculator to model how different commission rates affect your flip profit, or our BRRRR Calculator to see the impact on your cash-on-cash return when you eventually sell.
Feasibility Analysis: The First Step
Before committing capital to any development project, a thorough feasibility study is essential. This analysis should cover:
Site assessment: Zoning restrictions, planning history, environmental constraints (flood zones, contaminated land, protected species), access and utilities, and neighbouring uses that might affect value.
Financial modelling: Total development cost (land + construction + professional fees + finance costs + contingency), Gross Development Value (GDV), and target profit margin. Most developers require a minimum 20% profit on GDV for speculative projects, or 15% for pre-sold schemes.
Market research: Comparable sales within 1km, absorption rates (how quickly similar units sell), target buyer profile, and pricing strategy. In Portugal, new-build apartments in Lisbon currently achieve €4,000-€8,000/m² depending on location and specification.
Use our Development Calculator to model your project's financial viability before making any commitments.
Planning and Licensing in Portugal
The Portuguese planning system (RJUE — Regime Jurídico da Urbanização e Edificação) involves several stages:
-
PIP (Pedido de Informação Prévia): Optional preliminary enquiry to the Câmara Municipal about what's permissible on a site. Recommended before purchasing land.
-
Licenciamento: Full planning application with architectural project, speciality projects (structural, electrical, plumbing, thermal, acoustic), and all required studies. Typical timeline: 3-12 months.
-
Alvará de Construção: Construction permit issued after licensing approval and payment of fees. Must be obtained before starting works.
-
Licença de Utilização: Occupancy permit issued after construction completion and final inspections. Required before sale or occupation.
Construction Cost Management
Construction costs in Portugal (2026) typically range from €1,200-€2,500/m² for residential projects, depending on specification level and location. Key cost drivers include:
- Structure: 25-35% of total construction cost
- Finishes: 20-30% (this is where specification choices have the biggest impact)
- MEP (mechanical, electrical, plumbing): 20-25%
- External works: 10-15%
- Contingency: Always budget 10-15% for unforeseen issues
Fixed-price contracts with experienced builders reduce risk but typically cost 10-15% more than cost-plus arrangements. For investment projects, the certainty is usually worth the premium.
Finance Structures for Development
Development finance differs significantly from standard mortgages:
- Land purchase: Typically requires 30-50% equity (banks lend 50-70% of land value)
- Construction finance: Drawn down in stages as works progress, typically at Euribor + 2-4%
- Mezzanine finance: Fills the gap between senior debt and equity, at higher rates (8-15%)
- Joint ventures: Partner with a landowner or investor to reduce equity requirement
The total finance cost (interest + fees) typically represents 8-15% of total development cost, depending on project duration and leverage level.
The Five Approaches to Property Valuation
Professional property valuers use several methodologies, often combining multiple approaches to arrive at a final opinion of value:
1. Comparable Sales Method (Market Approach)
The most common method for residential property. It involves analysing recent sales of similar properties in the same area and adjusting for differences in size, condition, location, and features.
Key adjustments include:
- Size: Price per square metre comparison, with diminishing returns for larger properties
- Condition: Deduct estimated renovation costs for properties in worse condition
- Location: Micro-location matters — same street can vary 10-20% based on orientation, noise, views
- Time: Adjust for market movement since the comparable sale date
- Features: Parking (+€15,000-€50,000 in Lisbon), terrace (+10-20%), elevator (+5-10%)
2. Income Approach (Capitalisation Method)
Used primarily for investment properties. The property's value is derived from its income-generating potential:
Direct capitalisation: Value = Net Operating Income / Capitalisation Rate
For example: a property generating €12,000/year net income with a 5% cap rate is worth €240,000. Cap rates in Portugal currently range from 3.5% (prime Lisbon) to 7% (secondary cities).